The hardest part of buying a first home in Ontario is not the mortgage. It is the pile of cash you need before the mortgage even starts. So the question we hear most often is simple: what help is out there to build that down payment faster?
Here is the honest answer, with every real option in 2026, what each one is worth, and how to combine them. Some are government programs. Some are private. Two of the most-recommended options online no longer exist, and we will flag those so you do not waste time chasing them.
Is there down payment assistance in Ontario?
Ontario does not have a single government program that hands first-time buyers a down payment grant. Instead, there is a set of tax-sheltered accounts and rebates that, stacked together, can add tens of thousands of dollars toward a home. The main options are the FHSA, the RRSP Home Buyers' Plan, the land transfer tax rebate, family gifts, and private programs like Zown's Down Payment Boost.
The key idea is stacking. No single option solves the whole down payment, but used together they compound.
Down payment assistance options in Ontario at a glance
- FHSA. Maximum value: $40,000 (plus growth); Type: Tax-sheltered account; Who it is from: You, via CRA rules
- RRSP Home Buyers' Plan. Maximum value: $60,000 ($120,000/couple); Type: Tax-free RRSP loan to yourself; Who it is from: You, via CRA rules
- Ontario LTT rebate. Maximum value: $4,000; Type: Tax rebate; Who it is from: Province of Ontario
- Toronto MLTT rebate. Maximum value: $4,475; Type: Tax rebate; Who it is from: City of Toronto
- Family gift. Maximum value: No limit; Type: Gifted funds; Who it is from: A relative
- Zown Down Payment Boost. Maximum value: $25,000; Type: Cash back: up to 0.75% base, up to 1.25% financed through Pine; at closing with a partner lawyer, 2-8 weeks otherwise; Who it is from: Zown (brokerage)
Source: Zown Realty, Ontario 2026
The First Home Savings Account (FHSA)
The FHSA is the best down payment tool most first-time buyers have access to, because it combines the two tax advantages that usually come separately.
- Contribution room: up to $8,000 per year, to a $40,000 lifetime maximum. Unused room carries forward (up to $8,000 at a time).
- Going in: contributions are tax-deductible, so they reduce your income tax like an RRSP.
- Coming out: withdrawals to buy a qualifying first home are completely tax-free, like a TFSA.
That combination is why we tell buyers to fund the FHSA first. A buyer in a 30% marginal tax bracket who contributes the full $8,000 gets roughly $2,400 back at tax time, which can go straight back into savings.
the FHSA lifetime limit, all of it tax-free when withdrawn for a first home
The RRSP Home Buyers' Plan (HBP)
The Home Buyers' Plan lets you borrow from your own RRSP to buy a first home, tax-free, as long as you pay it back.
- Withdrawal limit: up to $60,000 per person, or up to $120,000 for a couple who both qualify.
- Repayment: you repay the amount to your RRSP over 15 years. If you do not repay a year's portion, that amount is added to your taxable income.
- Combining: since 2023 you can use the HBP and the FHSA for the same purchase.
The catch worth understanding: the HBP is a loan to yourself, not free money. You are moving retirement savings forward in time. For many first-time buyers that trade is worth it, but it is a decision, not a freebie.
The Ontario and Toronto land transfer tax rebates
Land transfer tax is one of the biggest closing costs in Ontario, and first-time buyers get a rebate on it.
- Provincial rebate: up to $4,000, which fully covers the provincial land transfer tax on homes up to about $368,000 and reduces it on more expensive homes.
- Toronto rebate: if you buy inside the City of Toronto, you also pay a municipal land transfer tax, and first-time buyers get a second rebate of up to $4,475.
A first-time buyer in Toronto can therefore save up to about $8,475 in combined rebates. These are claimed through your lawyer at closing, so they reduce the cash you need on closing day. We break down the full closing bill in our complete first-time buyer guide.
What about family gifts?
A gifted down payment from an immediate family member is common and fully allowed in Canada. Lenders will ask for a signed gift letter confirming the money is a genuine gift and not a loan. If your family is in a position to help, a gift is often the fastest way to reach 5% or 20%.
Programs that no longer exist (do not chase these)
Two options show up constantly in older articles and are no longer available:
- The federal First-Time Home Buyer Incentive. This shared-equity program stopped accepting new applications in March 2024. It is closed.
- Older provincial down payment loan pilots. Various one-time municipal or provincial pilots have opened and closed over the years. Always confirm a program is currently accepting applications before you build a plan around it.
Zown's Down Payment Boost: private assistance that stacks
Every option above is something you save, borrow, or claim. The Down Payment Boost is different: it is money a brokerage gives you.
Zown gives eligible Ontario buyers a share of the commission it earns as a Down Payment Boost of up to 0.75% of the purchase price, rising to up to 1.25% (capped at $25,000) when they finance their purchase through Zown's preferred mortgage partner, Pine.
When you close with one of Zown's partner lawyers, the Boost lands at closing, so it works as extra savings in your pocket right when you need it: it offsets your closing costs and the expenses that hit right after you get the keys, and lowers the total cash you need to have saved to buy. If you use your own lawyer instead, Zown pays the Boost once it receives its own commission from the seller's brokerage, typically 2 to 8 weeks after closing (Zown can't advance the funds sooner without putting them at risk in a lawyer's trust account if a deal were to fall through). On a $700,000 home financed through Pine, the Boost is up to $8,750.
How the Down Payment Boost scales with price (financed through Pine, capped at $25,000)
- $500,000. Down Payment Boost (up to 1.25%): $6,250
- $700,000. Down Payment Boost (up to 1.25%): $8,750
- $1,000,000. Down Payment Boost (up to 1.25%): $12,500
- $2,000,000. Down Payment Boost (up to 1.25%): $25,000 (capped)
Source: Zown Realty. Without Pine, the boost is up to 0.75% of the purchase price. The Boost is capped at $25,000. Eligibility applies.
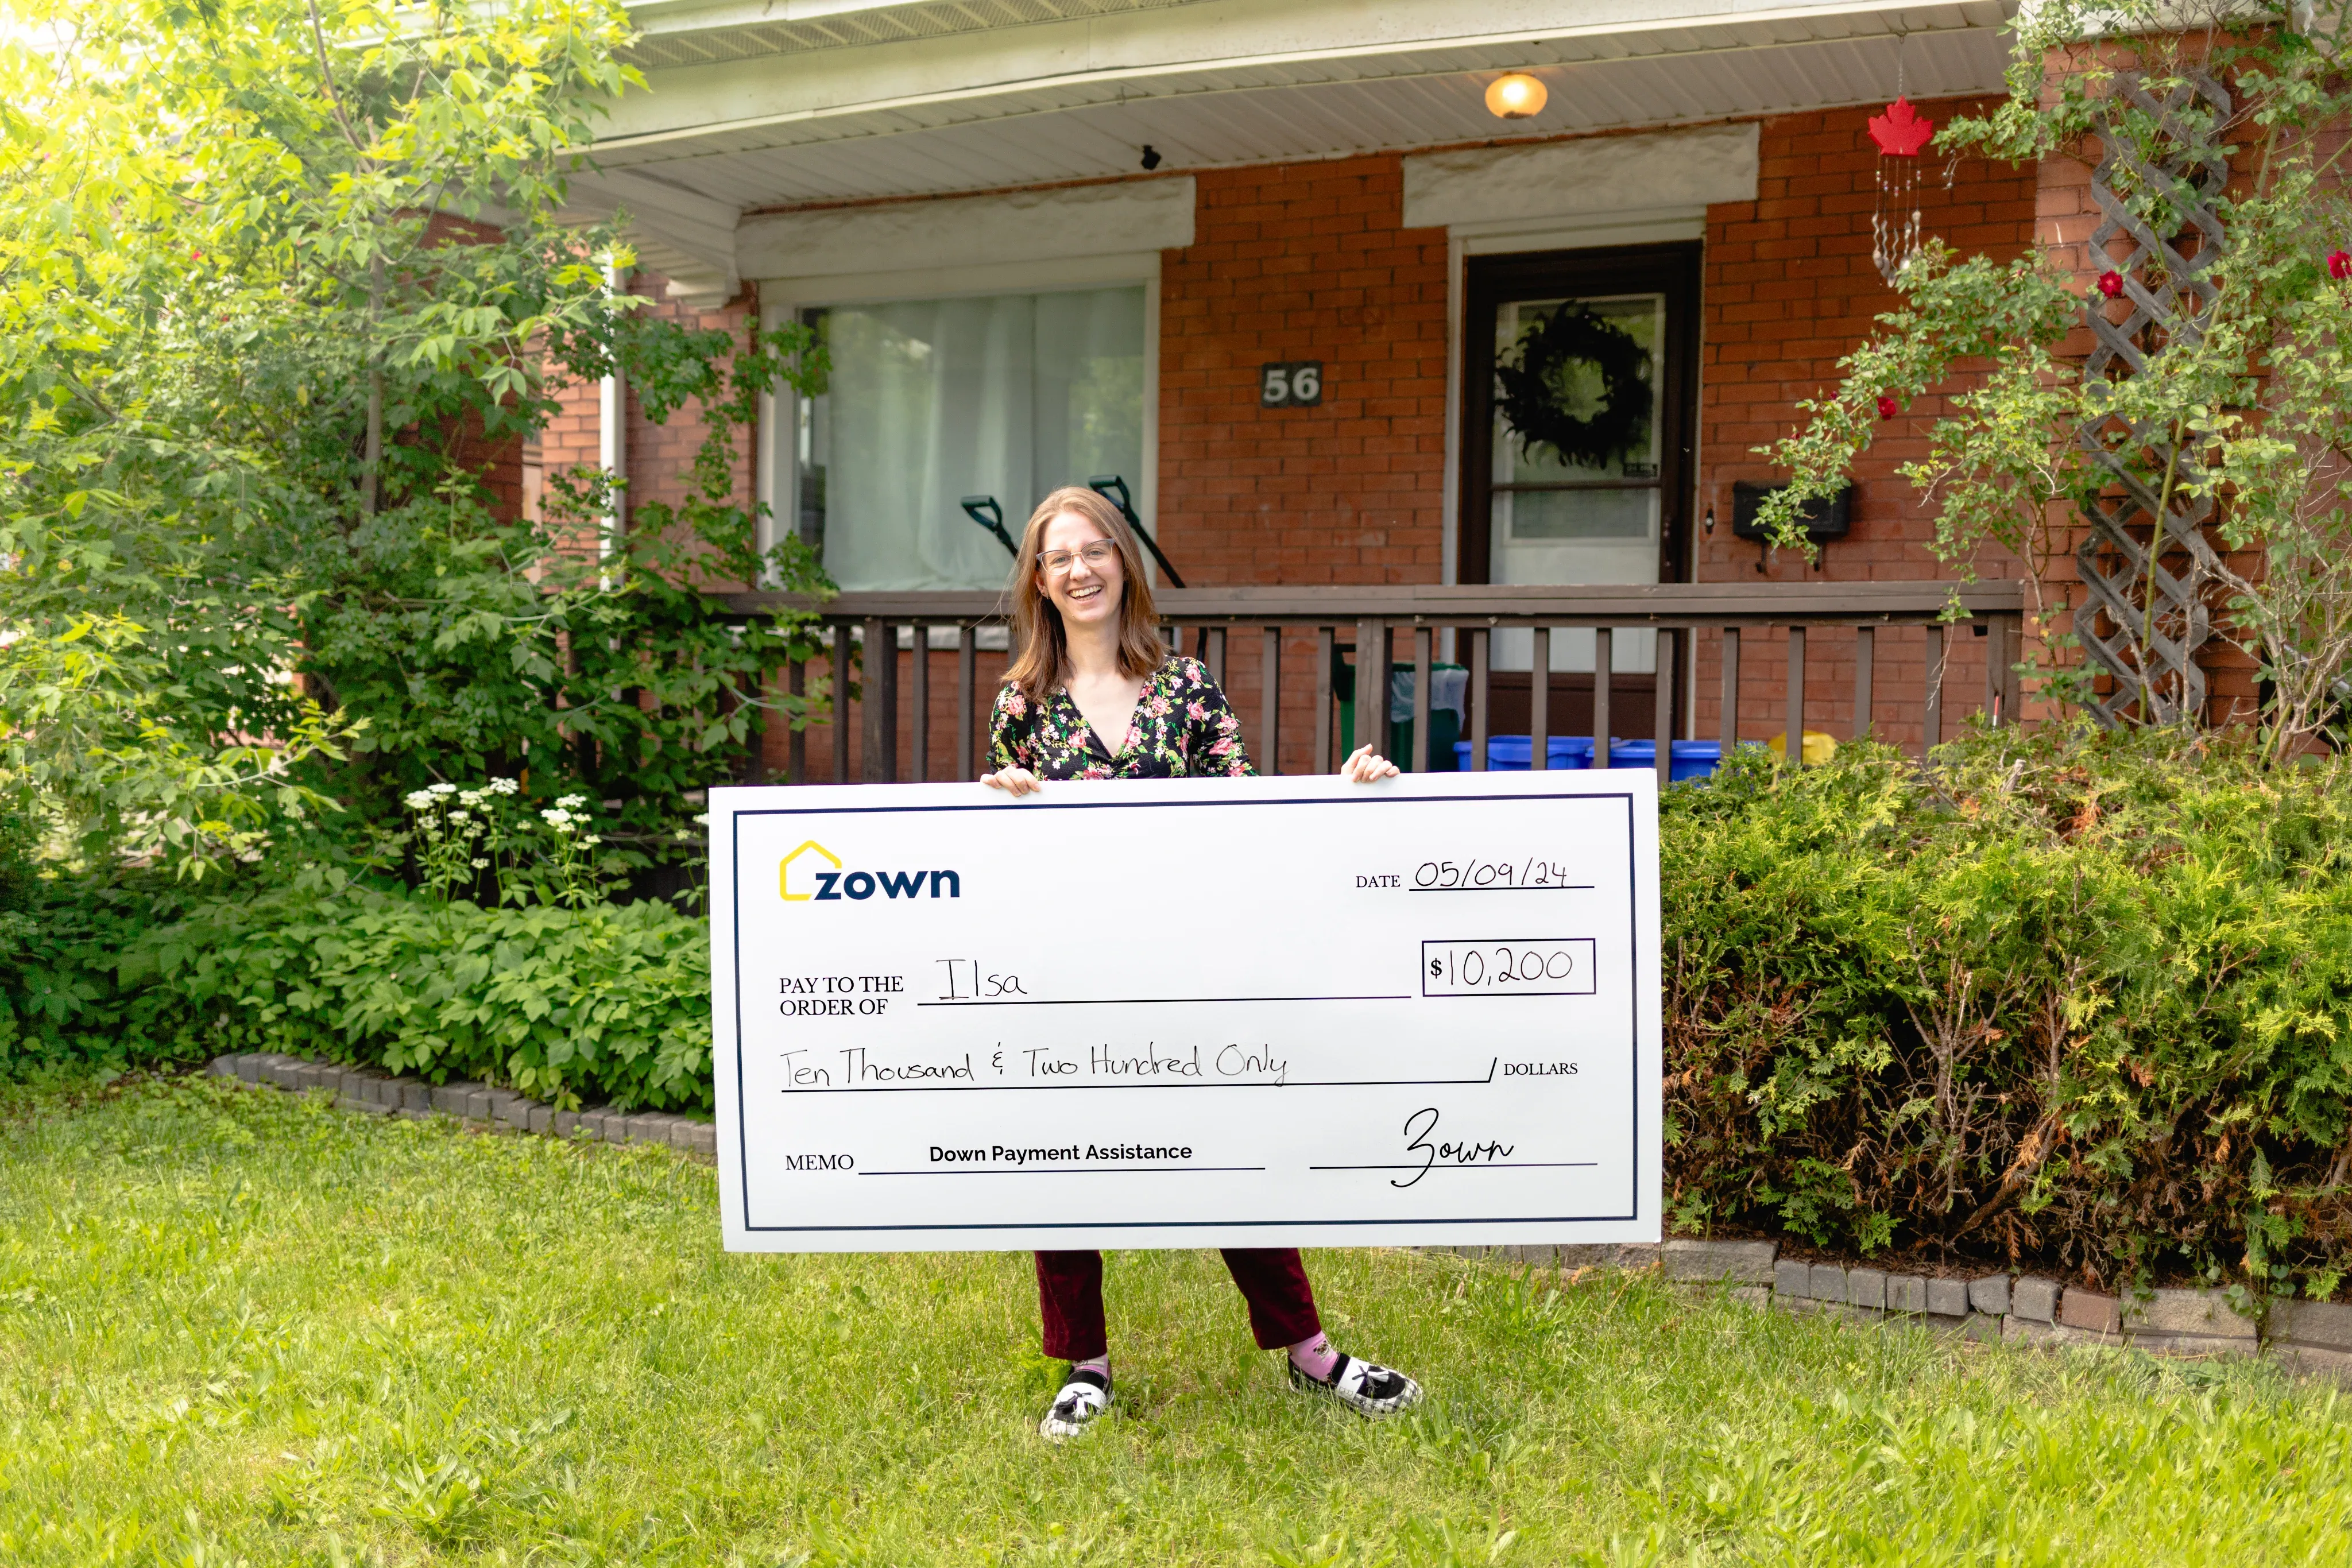
The Boost is not a government program and it is not a loan you repay. It is Zown choosing to return commission it would otherwise keep. More than 800 Ontario families have used it so far, totaling over $7 million given back.
Ontario families who have used Zown's Down Payment Boost to buy
How to stack it all: a real example
Take a couple buying a $700,000 first home in Ontario. Here is how the options combine:
- FHSA: they each contributed $16,000 over two years, so $32,000 saved plus the tax refunds they reinvested.
- HBP: they add $20,000 from RRSPs.
- Down payment: the $45,000 minimum on a $700,000 home is covered, with room to spare toward closing.
- Land transfer tax rebate: up to $4,000 back at closing (more if in Toronto).
- Down Payment Boost: up to $8,750, financed through Pine and closing with a Zown partner lawyer, offsetting their closing costs.
None of these alone gets them there. Together, they turn "we need years more" into "we can buy now."
See your personalized Down Payment Boost estimate →
Last updated July 27, 2026. This is general information, not financial or legal advice. Confirm current program rules and your eligibility before relying on any figure here.